Perth Amboy Elite Roofing brings more than 20 years in the trade to roofing in Manville, and here the work often begins with a question most towns never raise. Where does this house sit against the borough’s flood damage numbers? We repair and replace roofs on detached houses and two-family homes, and we want every owner to see each cost plainly before a contract is signed.
A leak call here starts indoors. We look in the attic or the top-floor ceiling as well as on the roof, so the water is traced to the spot where it actually gets in, not just to the stain. Then we tell you straight whether the roof can be repaired, and only after that do we talk about replacement. In Manville, the smaller honest number is often the one that serves an owner best.
Our written scopes break tear-off, decking, underlayment, flashing, ventilation and gutters into separate lines. An owner can compare two estimates item by item, or carry the page to the borough before deciding anything. The sections below explain why that conversation belongs before the work on a Manville house, not after it.
Ida’s Record Crest and Manville’s Substantial Damage Letters
The Raritan at 27.66 Feet
On September 2, 2021, Ida pushed the Raritan River at Manville to 27.66 feet, the highest reading on record at that gauge. The prior record was 27.1 feet, set by Floyd in September 1999, and Irene reached 26.24 feet in August 2011. Flood stage at the Manville gauge is 14 feet, so Ida’s crest came in at nearly twice that mark.
The water flooded most of the town. The Millstone and Raritan meet in the borough’s northeastern corner, and Lost Valley, the low ground between them in eastern Manville, is reached only through the Kyle Street tunnel and the Bridge Street bridge. After Ida the state adopted a buyouts-only approach for parts of Manville, Lost Valley among them, and gave priority to homes declared substantially damaged.
Manville also sits in National Weather Service forecast zone NJZ010, Somerset, served by the Mount Holly office, and the Raritan gauge at Manville is the forecast point to watch when heavy rain is coming. When a river forecast climbs toward flood stage, we hold off on tear-off. We would rather reschedule than leave a house open with the river rising.
Over 200 Houses Found Substantially Damaged
Once the water receded, the borough sent field teams to more than 500 houses and ran the findings through FEMA’s Substantial Damage Estimator software. Over 200 homes were determined to be substantially damaged. For each of those owners, the determination changed what could happen next with the house, whether they meant to repair it, sell it or stay.
The borough’s handout lays out three choices for a substantially damaged house: challenge the determination, sell through the state’s Blue Acres program, or elevate. A buyer of a house with that status receives a Temporary Certificate of Occupancy until it is lifted and signs an affidavit. None of this is roofing, yet all of it shapes what a roof estimate means on that street.
Where a Roofer Fits
We are roofers, and we stay in that lane. We do not make, challenge or advise on substantial damage determinations, and we do not prepare floodplain or buyout paperwork for anyone. What we can offer is a clear written roof scope with every cost broken out, one an owner can take to the people who actually make those calls.
Our contracts follow New Jersey’s home improvement rules, including the three-day cancellation notice, which gives an owner room to call the borough after signing if a question comes up late. Still, the better order is the borough first and the signature second. A week spent getting a clear answer is time well spent.
Looking for roofing closer to Somerville? See Roofing Services in Somerville.
The 50 Percent Line and the Rules Manville Added in 2022
What ‘Damage of Any Origin’ Means
Federal floodplain rules at 44 CFR 59.1 define substantial damage as damage of any origin where restoring the structure to its before-damaged condition would cost 50 percent or more of its market value before the damage occurred. The phrase ‘any origin’ is worth reading twice. The test is built around the cost of restoration, not around what caused the harm.
The same section defines substantial improvement as any reconstruction, rehabilitation, addition or other improvement whose cost equals or exceeds 50 percent of market value before the work begins. Both tests set a dollar figure against the value of the structure. That is why an owner near the line is wise to see every cost written down before choosing a path.
Cumulative Damage Since November 2022
In November 2022 Manville adopted a cumulative definition of substantial damage. In the borough’s own words, future flood damage repair numbers will be added to the Ida numbers, and if the total is over 50 percent, the homeowner will receive a substantial damage letter. For a house that came close after Ida, the earlier figure did not go back to zero.
That handout speaks of flood damage repairs. It does not spell out how other work on the same house is treated, and we will not guess at it for you. If you are unsure whether a project enters that running total, the borough’s floodplain manager is the person to ask, and we would rather you ask before we start than after.
The 500-Year Floodplain Comes Into Play
The borough’s November 2021 notice said only homes in the 100-year floodplain, the AE Zone, were regulated under its flood damage prevention ordinance. Since November 2022 Manville regulates the 500-year floodplain as well. The reason the borough gives is plain: FEMA’s flood maps for Manville are significantly out of date.
In practice, more houses now fall inside the regulated area than an older map would suggest. An owner who assumed the floodplain question skipped their street may want to confirm that before planning major work. The borough’s floodplain management consultant, Cleighton D. Smith, PE CFM, handles these questions alongside the Manville Building Department.
Pricing Roof Work on a House Near the Threshold
A Scope Someone Else May Read
On a house that already carries an Ida damage figure, a roof estimate is a document other people may read. That is why each part of our scope stands on its own line, with no single lump sum hiding the pieces. A floodplain manager, a lender or an insurance carrier can see what each item costs and judge it on its own terms.
The Manville Building Department answers at (908) 725-9478, extension 117 or option 4, and Frank LaGuarina is the construction official. We suggest owners near the line make that call with our scope in hand before signing anything. Whatever answer comes back belongs in your decision, and it should come from the borough rather than from a roofer.
Repair Before Replacement
Because the dollar figure carries weight here, we begin with the smallest fix that will actually last. A leak traced from the attic to one cracked pipe boot or a lifted run of step flashing may call for a repair, not a new roof. We say so directly, and replacement enters the conversation only when a repair would not hold.
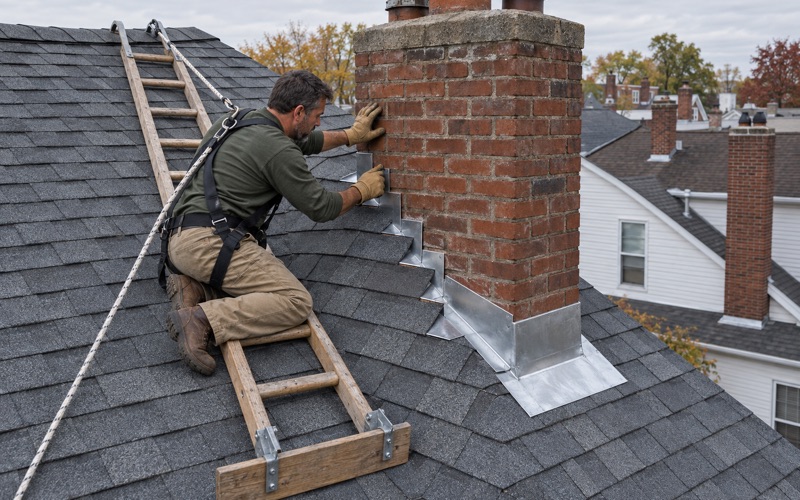
When replacement is the right call, the scope still separates what the roof needs from what is optional. A ridge vent with soffit intake, an ASTM D1970 ice and water barrier at the eaves, or new seamless aluminum gutters can each carry its own price. Step, counter and chimney flashing is replaced with the roof rather than reused, and you decide which optional lines go ahead and when.
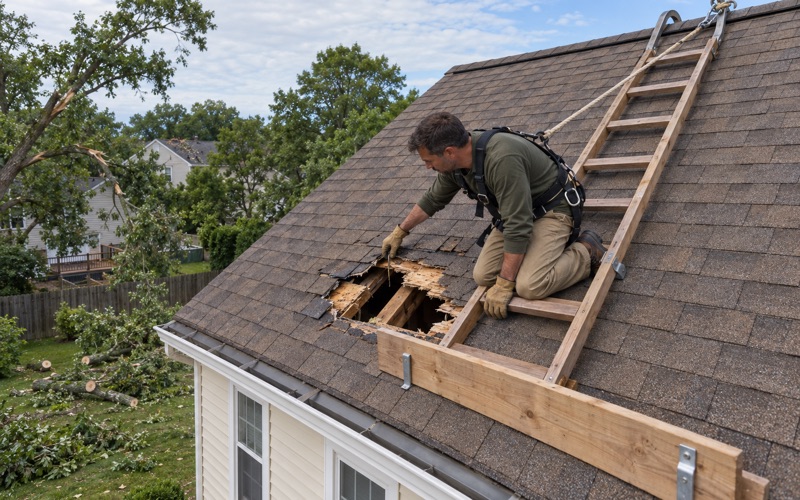
Decking is the one cost nobody can see in advance. If we find damaged sheathing once the old roof is off, we photograph it and show you before replacing a single board. The per-sheet price is already set in the contract, so the final total cannot climb without your knowledge and your approval.
Two-Family Houses With Tenants Upstairs
Nearly a quarter of Manville’s housing units sit in two-unit buildings, and plenty of them have tenants on one floor. We schedule those jobs with the tenants in mind, so the people upstairs know when the crew arrives and where we need access. At the end of every work day we clean the sidewalk, yard and gutters and run a magnet sweep for roofing nails.
Elevation, Blue Acres and Where the Roof Fits
When a House Must Be Lifted
Under the borough’s handout, a substantially damaged house that stays in place must be elevated so the first floor sits at least four feet above FEMA’s Base Flood Elevation. The basement is filled, utilities are relocated and flood vents are installed. The borough puts the cost at $100,000 to $150,000 or more, and its 2021 notice said FEMA allows up to six years to comply.
A house that gets lifted takes its roof along, so the plan for one should fit the plan for the other. An owner weighing elevation may want to time any roof work so the two jobs do not collide or overlap. Once the elevation contractor’s schedule is known, we are glad to talk through sequencing and what the roof needs in the meantime.
Blue Acres and the Buyout Areas
According to the borough, NJDEP’s Blue Acres program has purchased more than 150 houses in Manville since the 1990s. A State Action Plan amendment says SRRP and HARP applicants within Manville’s high flood risk area are offered a buyout instead of rehabilitation or elevation. Those decisions run between the owner and the state, and we have no part in them.
If your house is part of that conversation, a large roof investment may not be the sensible first step. We can still stop an active leak with a modest repair while you wait for answers, and we will tell you if that is all the roof needs for now. The buyout question itself stays with you and the state.
Insurance, Compliance Money and the Roof
Flood claims and roof claims are separate matters, and we do not speak for any policy. The borough notes that Increased Cost of Compliance coverage, up to an additional $30,000, comes with NFIP policies and not with private flood insurance, and it is meant to help owners meet floodplain requirements. Ask your own agent what your policy actually pays for.
For wind or storm damage to the roof itself, we photograph what we find and write it up for your own claim. When you ask, our crew will meet the insurance adjuster at the house and walk the roof with them. We document the damage, and the carrier decides what its policy covers.
- 20+ Years in Roofing
- Itemized Written Estimates
- Attic-to-Roof Leak Tracing